Recover more on every car. Sign more of the injury cases behind them.
Cara pressure-tests the insurer's number, whether the car was totaled or repaired, and returns an evidence-backed analysis under your firm's name. That's new revenue on the clients you already have. It's also a reason to say yes to the property-damage callers you turn away today, which is where the next injury case comes from.
If your firm buys TV, radio, or billboards, you're already paying for the property-damage calls you turn away. Drag the slider to see what answering them is worth.
The repaired pool is where diminished value lives, and it's the larger of the two: 2.3× the total-loss pool at these settings.A DV report is $150 and a total-loss report $200, each charged only when it supports 10%+ added value. A check that finds nothing costs nothing.
Green = typical range; dark tick = our default. Estimates only, not a projection of outcomes. Report fees aren't netted out.
A citable second opinion your client, and opposing counsel, can't wave off.
A jury found one insurer had quietly shaved roughly 9% off the comparable prices behind its offers. On a $30,000 vehicle, that one line is about $2,700, subtracted before the claimant ever saw the number. Cara surfaces adjustments like this with the comparable listings and the math attached, so your demand rests on evidence, not assertion.
Sources: AppraiseItNow total-loss appraisal review, 2025 (small sample; a reported average uplift, not a guaranteed outcome). Comparable-price “negotiation” adjustment established by an Arkansas jury verdict, via Autobody News. Some offers are fair; Cara will say so. Cara provides analysis, not legal advice.
Three steps, then try it yourself
Built to slot into how your team already works a property-damage file. No new system to learn.
Send what the insurer sent you
A total-loss valuation (CCC ONE®, Mitchell WorkCenter™, Audatex Autosource®, + others) or the repair estimate on a car that was fixed, plus anything the paperwork missed.
Cara runs the methodology
Line-by-line check against real listings for a comparable vehicle, plus your state's sales tax and required fees, with every adjustment itemized.
Get a packet from your firm
A white-labeled analysis, comparable listings, and a ready-to-edit counter-letter under your firm's name.
See it on one of your files
Upload the insurer's valuation or a repair estimate from a real file. Pick which one you're sending, and Cara emails the matching analysis back. No account, no card.
Every crashed car carries one of two claims
Which one applies isn't your client's choice. It's the insurer's, made when the repair estimate comes in against what the car was worth. Send the document that decision produced, and Cara runs the report that fits.
Total-loss report
The insurer declared the car unrepairable and paid its own estimate of what the vehicle was worth. Cara re-tests that valuation against live listings for the same car and itemizes every adjustment sitting behind the offer.
- Every insurer adjustment itemized with dollar impact
- Live comparable listings, archived as exhibits
- Counter-letter under your firm's letterhead
Diminished-value report
The car was fixed and handed back. It now carries the accident on every history report a future buyer will pull, and the market prices that in. The insurer's offer, where there is one, usually doesn't.
- Pre-loss market value vs. the value after repair
- The insurer's 17c math recomputed, step by step
- Same exhibit-backed packet format
Same evidence standard on both: real comparable listings, every adjustment itemized, and the finished packet under your firm's letterhead. No subscription, no minimum, no per-seat fee, and a report that finds the insurer's offer fair costs nothing. Case-management integration is built for your firm at no additional cost. Cara provides an independent, evidence-backed analysis, not legal advice or representation.
Leverage on the property-damage side of the file
Total-loss valuations and diminished value are where insurers quietly keep your clients' money. Cara turns that into recoverable dollars without adding hours to your team's plate.
White-labeled, from your firm
The analysis and counter-letter carry your firm's name and letterhead, with nothing to attribute to a third party. Hand it straight to the client or attach it to a demand.
Defensible methodology
Every conclusion ties back to real, current comparable listings, itemized adjustments, and state tax/fee rules: evidence you can cite, not a black-box estimate.
Minutes, not hours
Upload the insurer's PDF, add anything the paperwork missed, and the packet comes back ready. No adjuster calls, no manual comps pull.
More per case
A stronger property-damage recovery lifts the total settlement, and your fee, on files you're already handling.
Priced flat, per report
$200 for a total-loss report, $150 for diminished value. No subscription, no seats, no surprises on the invoice.
Client data handled cleanly
Documents are encrypted on upload, used only for the analysis, and deleted after 30 days. Never sold or shared.
Speak to a personal injury attorney who uses Cara on his own files
David Glass is a customer, not a spokesperson. He's been running his total-loss files through Cara since February and offered to take calls from firms considering it; we don't pay him for that, or for anything on this page.
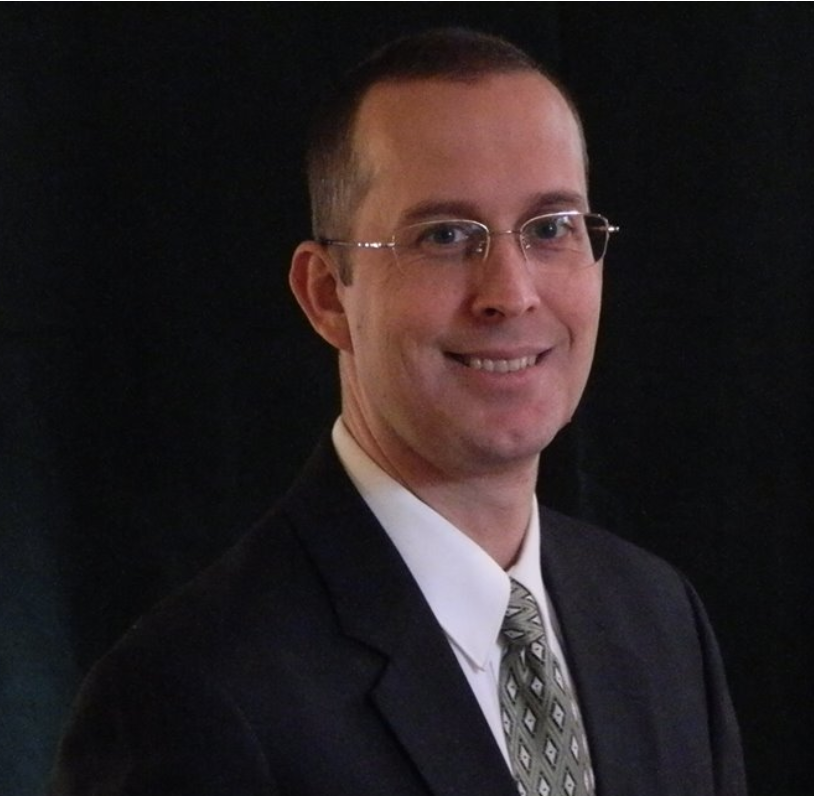
- 26+ years in personal injury, working his own files
- Cara customer since February 2026
- Takes these calls himself. Not on our payroll, not a script
Since February: 26 total-loss files through Cara, 19 PD-only matters he used to refer out, and 2 injury clients who first called about the car.
Worth asking him about:
- Whether it actually moves an adjuster. What the carriers did when he sent the packet, including the times they didn't budge.
- If the economics work on a book like yours. Bring your total-loss volume; he'll tell you plainly if he thinks it won't.
- What the first month looked like. How he fit it into intake without hiring or retraining anyone.
The call is a conversation about the tool, not legal advice, and doesn't create an attorney-client relationship. David's results are his own; yours will depend on your vehicles, offers, and jurisdiction. We don't publish client case figures on this page.
Book a 15-30 minute demo
We'll walk through a real redacted run, show the white-labeled packet your firm would send, and set you up for your first cases.
Pick a time nowopens our booking calendar- See a live analysis on a redacted total-loss offer
- Preview the packet under your firm's name
- Walk through pricing and onboarding for your team
- Ask us to include an attorney who uses Cara
It goes where your files already live
If your firm runs a case-management system, we connect to it and the report lands on the matter. If it doesn't, you get a plain workspace instead: one list, one upload box, nothing to administer.
Pick the one that describes your office:
We build the connection to it, free.
Name the system your office already runs and we do the integration work at no charge. Your staff sends the valuation the way they already send documents, and the finished report and counter-letter come back attached to the matter. No new login for your paralegals, no second place to check, no migration, no admin.
- Integration built and maintained by us, at no cost to the firm
- Reports land on the matter your team is already working
- Don't see your system? Tell us and we'll build it for your firm
Built on request during onboarding. Typical turnaround is under two weeks.
Documents are encrypted on upload, used only for that case's analysis, and deleted after 30 days. Never sold or shared. Cara provides analysis, not legal advice.
The insurer decided what the car was worth. Check the work.
A total-loss valuation is a stack of adjustments applied to comparable vehicles the carrier picked. Most of it is defensible. Some of it isn't, and none of it is visible to your client as anything but a total.
A valuation report
- Comparable vehicles the carrier selected, adjusted for mileage, options, trim, and condition.
- Condition and “negotiation” adjustments applied to those comps, usually downward and rarely explained.
- State sales tax and mandatory title and registration fees, sometimes short and sometimes absent.
Rebuild it from the market
- Pull live listings for a genuinely comparable vehicle and price the car against them.
- Itemize every adjustment the carrier made with its dollar impact, including the ones with no stated basis.
- Check the tax and fee lines against your state's rules, then hand back a counter-letter on your letterhead.
The car is fixed. It's still worth less.
After a repair, the accident follows the car onto every history report a future buyer will pull. The market prices that in; the insurer's offer usually doesn't. A Cara diminished-value report measures the gap between the pre-loss market value, taken from real comparable listings, and the value the accident record takes away, showing the math line by line.
The 17c formula
- A base loss capped at 10% of the vehicle's book value. The ceiling is set before anyone looks at the car.
- Then a damage-severity multiplier, then a mileage multiplier. Each step can only take the number down.
- No regulator requires any of it. It's a convention the industry adopted, and it arrives presented as the answer.
Audit it, then measure the market
- Measure the pre-loss market value from live comparable listings for the same vehicle, independent of the insurer's number.
- Recompute the insurer's 17c worksheet deterministically, and when they provided their own figure, audit it against theirs, showing where the cap and the multipliers suppressed the result.
- When the claimant has a real instant cash offer on the repaired car, that measured floor anchors the number. All figures go into the packet, with the listings attached as exhibits.
“We don't argue with the insurer's formula. We audit it, then show the market's answer next to it.”
Pulled from live market listings for a comparable vehicle at the time of the claim, archived as exhibits.
A deterministic recompute of the insurer's own math, showing each step and what it removed.
Traced to a published source: state tax and fee rules, valuation guides, case law.
Every figure in the packet is one of those three. Nothing is authored. Diminished-value recovery depends on state law and claim type: third-party claims are the standard case, while first-party recovery turns on the policy language and the jurisdiction; the report intake screens for it. Cara provides analysis, not legal advice, and is not a substitute for a licensed appraiser.